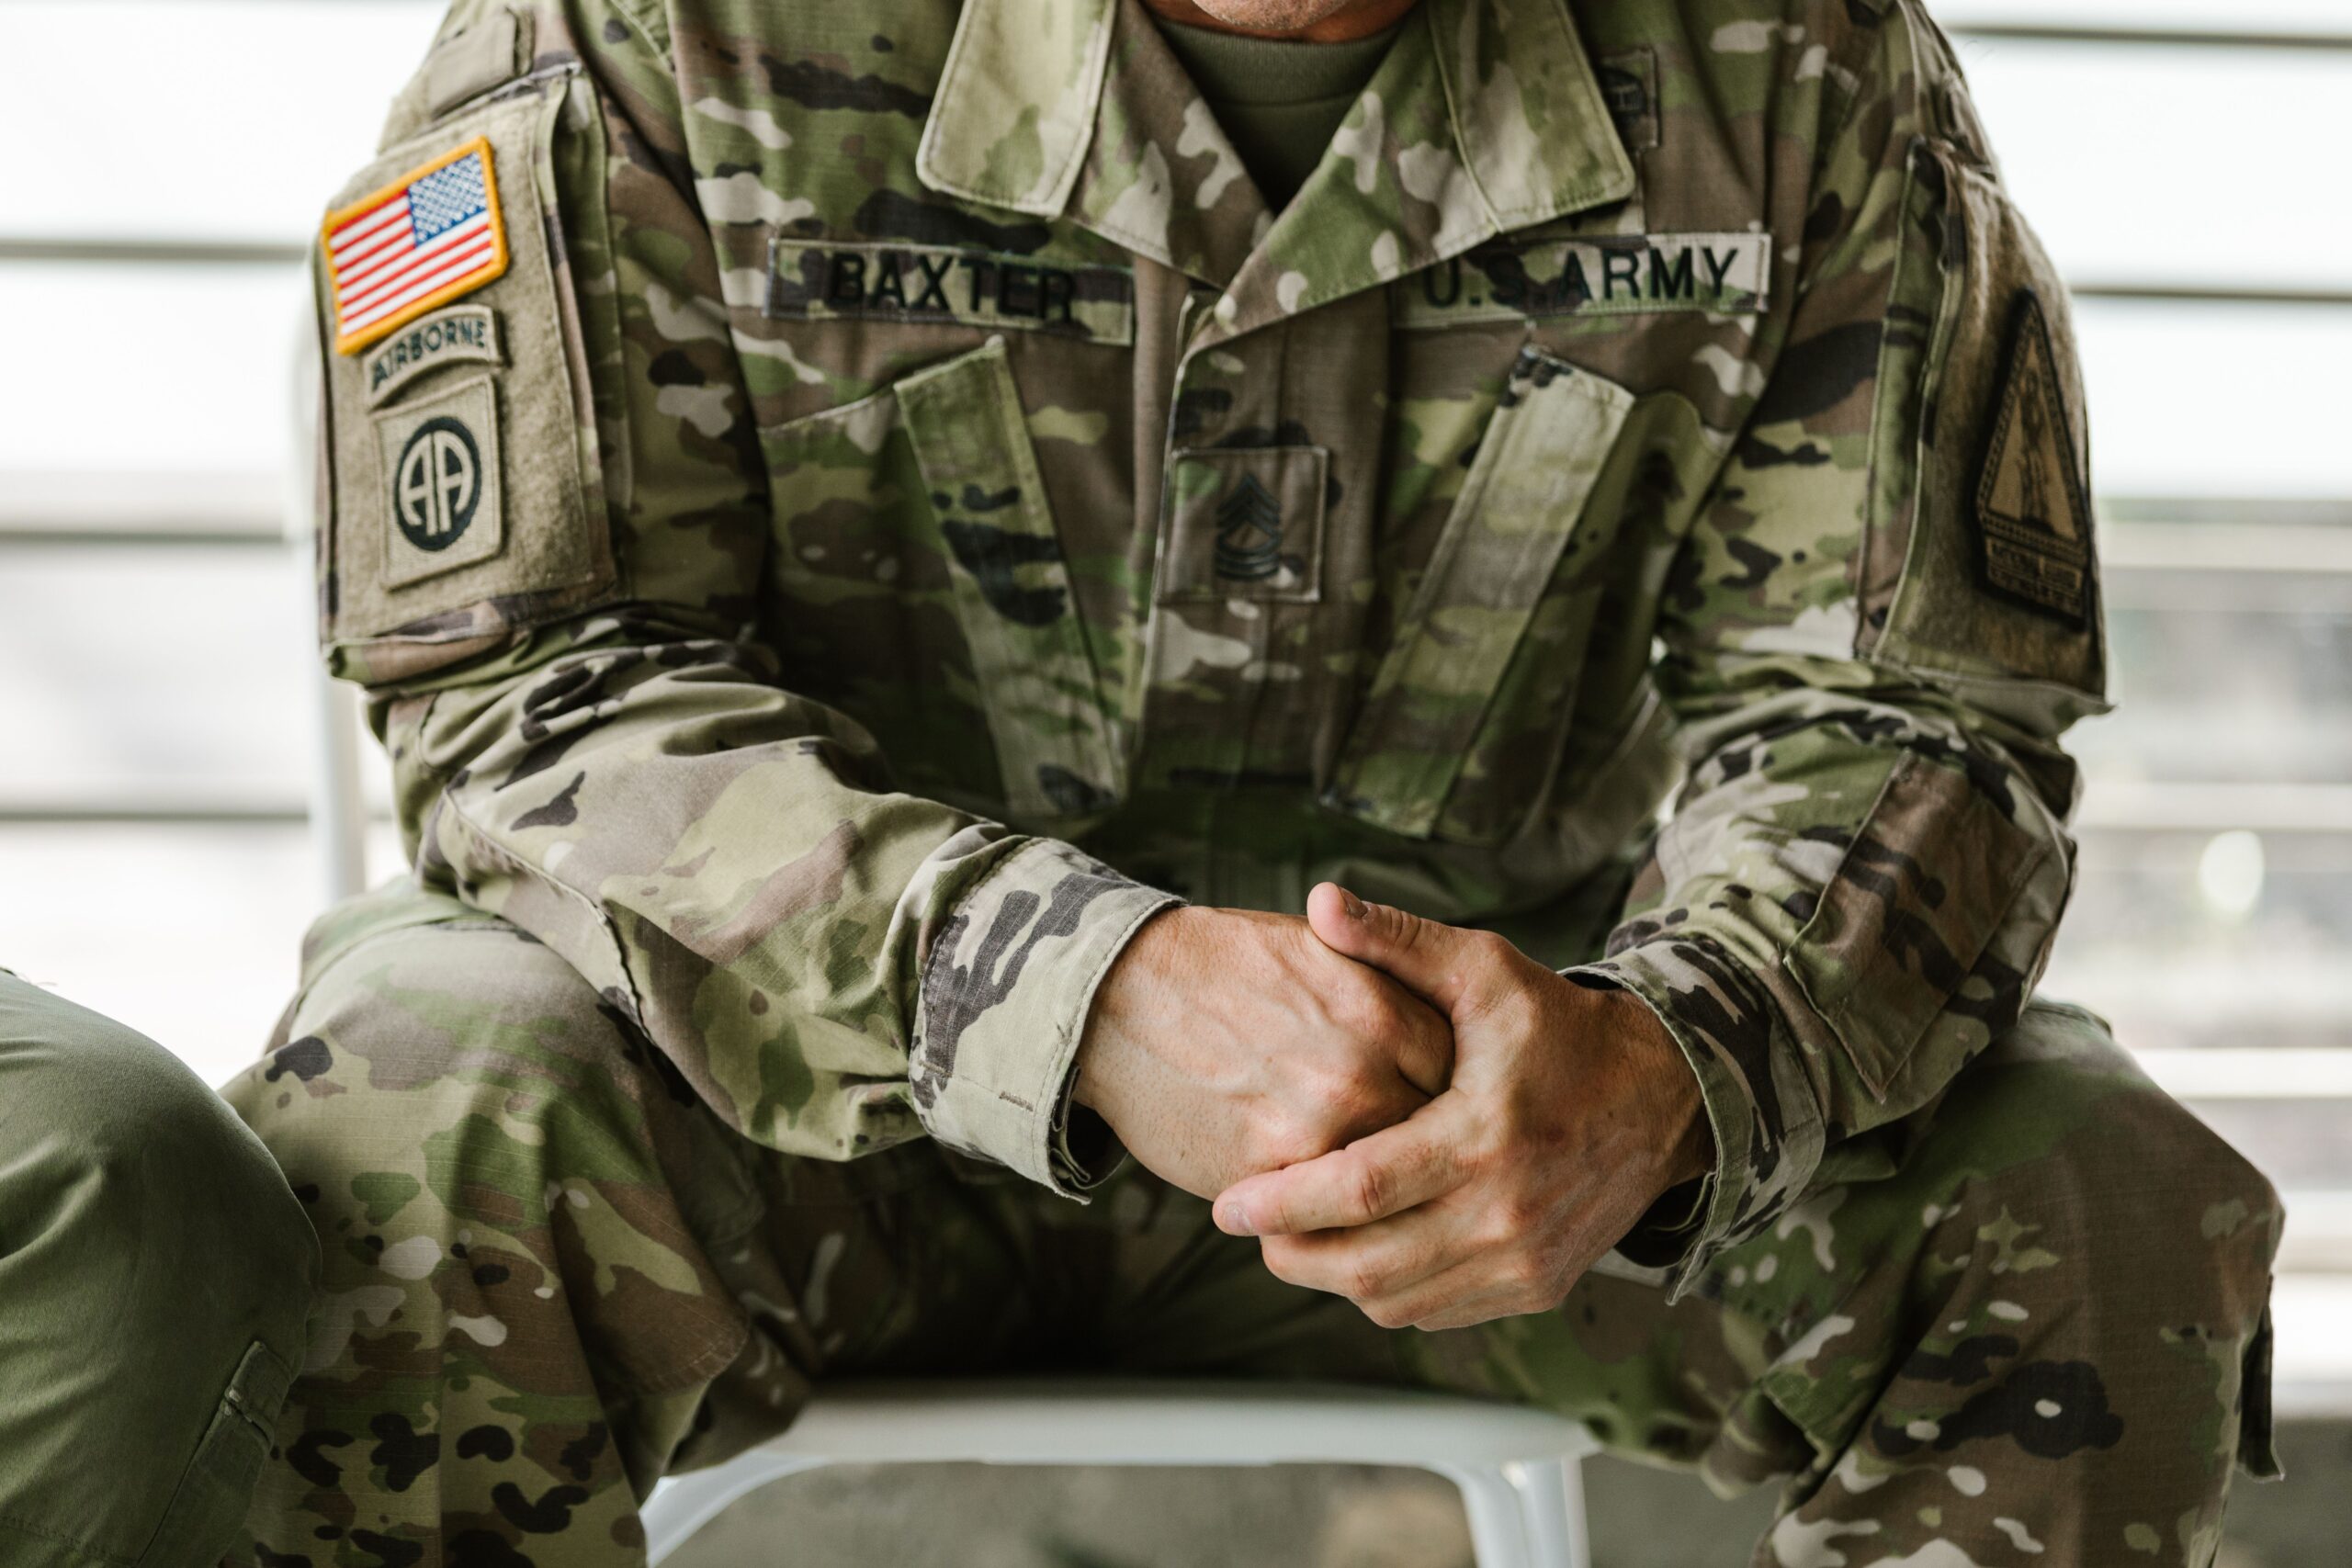
Several of us on the Premier Homes team come at this one personally, as veterans and as military kids who grew up moving every few years. We know the mindset: the compressed house-hunting leave, the PCS orders that don’t leave much room for a slow decision, the instinct to research everything twice before trusting anyone with it. We also work closely with VA-loan specialist lenders who handle this every day, so this is the guide we’d actually hand a friend who just got orders to Nellis.
 The VA Loan Advantage
A VA loan still does what it’s always done best: it lets eligible veterans, active-duty service members, and some surviving spouses buy with no down payment and no private mortgage insurance. For 2026, first-time users pay a 2.15% funding fee with zero down, which drops to 1.5% with 5% down and 1.25% with 10% down. Veterans receiving VA disability compensation at any rating, along with Purple Heart recipients, are exempt from the funding fee entirely. And while VA loans technically have a $832,750 baseline limit for most counties in 2026, veterans with full entitlement can actually finance above that with no down payment in most cases, since the VA effectively removed hard loan limits back in 2020.
The Hidden Superpower: Assumable Loans
This is the part most people don’t know, and it matters a lot right now: every VA loan is assumable by law, meaning a qualified buyer can take over the seller’s existing loan, interest rate and all. With average rates sitting around 6.5% in 2026, a VA loan that was originated back when rates were in the 2.5% to 3.5% range can save a buyer several hundred dollars a month on a comparable balance. The assumption funding fee is just 0.5%, and any creditworthy buyer can assume the loan, veteran or not, though a veteran-buyer using their own entitlement frees up the seller’s entitlement immediately. It’s a genuinely underused tool on both sides of a transaction, and it’s worth asking about whether you’re buying or selling.
Nevada’s Veteran-Friendly Tax Picture
Nevada has no state income tax at all, which matters more than people expect once military retirement pay enters the picture, that pension isn’t taxed here the way it would be in many other states. On top of that, Nevada offers a veterans’ property tax exemption for any veteran with 90+ consecutive days of active duty and an honorable discharge, and a separate, larger exemption for veterans with a permanent service-connected disability: $18,200 of assessed value at 60-79% disability, $27,300 at 80-99%, and $36,400 at 100% for the 2026-27 fiscal year. These stack with other savings, and they’re worth asking your lender or a tax professional about directly since eligibility details can shift year to year.
Where Military Families Actually Live
Most Nellis-assigned families end up in a handful of spots depending on commute preference. Sunrise Manor sits closest to the base, often around a 12-minute drive to the gate, with a mix of established and newer homes. North Las Vegas, just west of the base, runs about 15 minutes and offers more new construction. Aliante, a master-planned community further north, runs closer to 18 minutes but tends to come with higher price points and more amenities. For families assigned to Creech Air Force Base near Indian Springs, about 45 miles northwest of Las Vegas along US-95, most either commute from northwest Las Vegas or use Nellis-area housing and make the longer drive, since Indian Springs itself is a very small town without much housing stock of its own.
What BAH Actually Buys Here
For 2026, Basic Allowance for Housing at Nellis runs $2,070 a month for an E-5 with dependents, with rates scaling up by rank from there. Combined with a zero-down VA loan, that monthly housing allowance often covers a meaningful chunk of a mortgage payment on a home in the $350,000 to $450,000 range, depending on rate and taxes, though it’s worth running your specific numbers with a lender before you start touring, since BAH varies by rank and dependency status and the math changes fast.
Timing a PCS Move the Right Way
House-hunting leave is short, so the families who have the smoothest moves usually get pre-approved before they land, line up a few homes to see in person ahead of time, and work with an agent who already understands PCS timelines rather than explaining the process from scratch. If you’re arriving from overseas or dealing with a compressed report date, ask your lender early about remote closing options and whether a VA appraisal timeline will actually fit your move window; that single conversation avoids most of the last-minute stress we see.
This is genuinely one of our favorite conversations to have, not just because we understand VA loans and the local base geography, but because a lot of us have lived this exact move ourselves. If you’ve got orders to Nellis or Creech, or you’re a veteran or military retiree settling in the valley for good, Premier Homes Real Estate can walk you through your VA loan options, connect you with lenders we trust, and help you figure out which side of the valley actually fits your commute and your family.
PCSing to Nellis or Creech, or settling into retirement anywhere in the Las Vegas valley? Contact Premier Homes today — our Real Estate, Business Brokerage, and Property Management teams work together so you get the whole team’s knowledge, not just one agent’s.